I have been in the industry for over 20 years, ten of which were focused on builder risk, and I have seen the market change many times over the years.
In my opinion, these are the three biggest factors impacting builder risk right now:
Project stalled
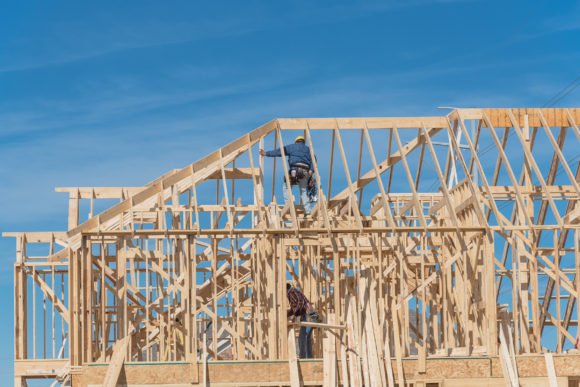
The number of builder risk submissions has increased compared to recent years, but the time from quote to binding is much longer. According to DUAL’s experience, a project used to take 90 days to complete binding, but now this time has been greatly extended.
On the eve of the IRMI Construction Conference, DUAL North America Builder Risk President Kaycie Cook identified three key factors impacting the builder risk market: project stagnation, future loss rate challenges and generational change.
Uncertainty is at the heart of stagnation. Tariffs and other geopolitical factors are disrupting supply chains in China and the Strait of Hormuz and increasing material costs for builders in risk spaces. For example, lumber typically comes from Canada, and tariffs have increased prices by about half, prompting builders to delay project starts in the hope that tariffs will ease. Other questions are more specific. The global rush to build data centers has increased power demand, resulting in combined cycle turbine lead times of five years, meaning any contingent loss of business intelligence associated with delays could be catastrophic.
“Spicy” loss rate
Despite market weakness, loss rates remain high. Builders risk claims always occur months after the policy comes into effect, and project delays extend the time even further. Underwriters need to remain disciplined and recognize that the impact of today’s decisions on loss ratios may not impact carriers for several years. Brokers play an important role in keeping underwriters informed about the latest information about their clients and the construction market as a whole.
Arson continues to be a significant loss, with many claims stemming from “not in my backyard” arson-related incidents. Recently, there have been a series of arson attacks in development areas in Salt Lake City, Utah, and Aurora, Colorado. Some operators have also reduced security requirements due to market weakness, which could lead to higher loss rates in the future.
Generation change
It’s great to see a large number of young insurance professionals, both brokers and underwriters, choosing to specialize in this area. Generational shifts and current market conditions are fueling an increase in creativity. There is more “out of the box” thinking across all disciplines, including some clever uses of artificial intelligence.
New entrants to the industry should be aware that the current overcapacity is unlikely to persist and that it is important to build strong, stable long-term partnerships with operators. This has always been a key focus of DUAL.
The way people build relationships across the industry is also changing. Creativity and innovation focus on unique activities such as cooking classes, yoga classes and using artificial intelligence to help plan different events. While activities may change, underwriting remains fundamentally a personal matter. One focus is on building trusted connections throughout the underwriting cycle to create great outcomes for clients, brokers and underwriters.
Like all insurance products, the market operates in cycles. Being aware of and on top of the current drivers of each cycle, and understanding how the market has historically responded to these drivers, can improve future decisions.
interested in builder risk?
Get automated alerts on this topic.