A federal appeals court in a case involving rain damage to a large solar farm in Georgia said that American Airlines Zurich could not reclassify the loss as one with a higher deductible after it paid part of the claim.
“Golfers can schedule. But in this case, insurance companies don’t,” US 11th the circuit court of appeals wrote in an Oct. 22 opinion.
Zurich America has a builder’s risk policy in place for First Solar, which in 2018 built a 200-megawatt solar farm near Warner Robins in central Georgia. Five heavy rain events in 2019 and 2020 caused water to accumulate on former farmland, causing extensive damage to solar modules.
Zurich adjusters determined that the damage was due to water damage rather than flooding, and Zurich made advance payments totaling $600,000 for the first three rain events. The policy provides a water damage deductible of $100,000 per incident.
But Zurich later changed its attitude and believed that the floods in 2019 and 2020 were actually flooding events. The deductible for flood damage in the policy is much higher – $2.5 million each time. Zurich argued that this meant all claimed losses were below First Solar’s policy deductibles and therefore no compensation was payable.
Lawsuits ensued. After a jury in the U.S. District Court for the Middle District of Georgia found in First Solar’s favor, the judge awarded $12.2 million, including prejudgment interest.
Both sides appealed parts of the ruling.
A key issue is the wording of the policy. Water damage is defined as “all damage caused by water, regardless of its source, whether driven by wind or not, except damage defined as flooding or caused by a designated storm.”
Zurich nevertheless insists that flooding submerged the solar farm. The First Solar team argued at one point that because the property was described as being on generally dry land and at least partially in a Category 3 flood zone (only moderate flood risk), it had to be considered water damage.
Even John Shaw, an insurance agent for the solar company, weighed in, urging Zurich and adjusters to consider the claim as being caused by water, not flooding.
No. 11th The Circuit Court of Appeals panel upheld the district court’s claims regarding the first three rainfall events and remanded the case for more consideration of the two later rainfall events. The appeals court’s opinion noted that its interpretation of the policy and the evidence showed that the higher flood deductible actually applied in this case.
But the court ruled that Zurich had waived its deductible, paid the first three flood claims and did not reserve the right to change the coverage determination.
“The central issue in this appeal is whether Georgia law allows an insurance company in a situation like Zurich’s to resort to redeployment, which is to accept a do-over after messing up the first time,” 11th Circuit Judge Embry Kidd wrote in the opinion. “Or, under Georgia law, did Zurich’s actions waive its right to apply the flood deductible after previously applying the flood deductible?”
The answer is “yes”: Zurich gives up the right hand and drives the drive into the woods. There is no scheduling.
The court also found that a strangely worded clause in the policy did not require legal proceedings to be commenced within 12 months of the incident. “We conclude, therefore, that the action arising out of the incorporation clause is not a limitation of action clause,” the judge wrote.
The full comments can be viewed here. The first solar complaint is here.
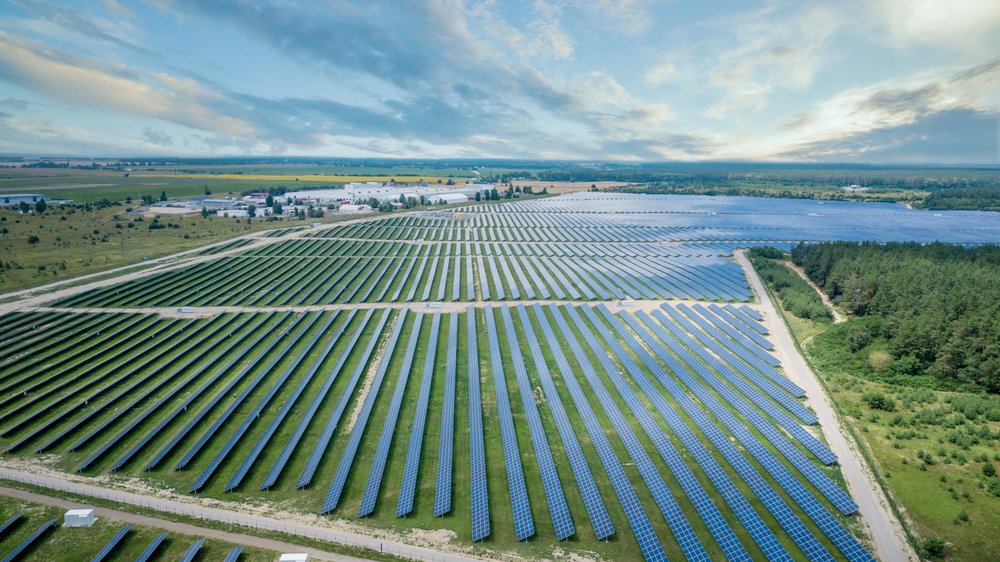
Top photo: Stock image of a solar power plant. (Deposit photo)
theme
Georgia Agribusiness Carrier
interested in agribusiness?
Get automated alerts on this topic.